Effective Strategies for Enhancing Financial Reserves in the United Kingdom
Understanding the Current Savings Behaviour of UK Households
Assessing income stability and spending habits is vital for households in the UK. This analysis uncovers weaknesses in financial preparedness, particularly in the face of economic downturns. Many families experience income variability, complicating their ability to consistently save. By examining these dynamics, individuals can adopt specific strategies to bolster their financial health and readiness for potential crises.
Households should break down their spending patterns and emphasise essential costs. This approach helps in pinpointing areas for potential savings, allowing families to redirect more funds towards financial reserves. Conducting regular evaluations of savings ensures individuals can make necessary changes, enhancing their preparedness for unexpected financial challenges.
What Makes Creating an Emergency Fund Essential?
Establishing a dedicated emergency fund is a crucial component of building financial resilience. This fund should be set up to cover unexpected expenses, such as vehicle repairs or job losses, which are common in the UK. By committing to save a fixed amount each month, individuals can gradually build a safety net that secures their long-term financial wellbeing and peace of mind.
An effective emergency fund usually contains three to six months’ worth of essential living expenses. This buffer is invaluable during financial instability. It is important to keep these funds readily accessible but distinct from day-to-day spending accounts, preventing the temptation of using savings for non-emergency situations.
Which Government Assistance Schemes Can Enhance Financial Stability?
The UK government provides various support schemes, including Universal Credit, Jobseeker’s Allowance, and housing benefits, offering extra layers of financial protection during crises. Exploring these resources enables residents to maximise their entitlements and secure the vital support necessary during economic hardships.
Staying updated on changes to government support schemes is essential, as eligibility criteria and available assistance can fluctuate. A comprehensive understanding of these resources empowers individuals to navigate difficult periods more effectively, thereby enhancing their financial stability and facilitating informed decisions about personal finances.
How Can Budgeting Methods Improve Savings?
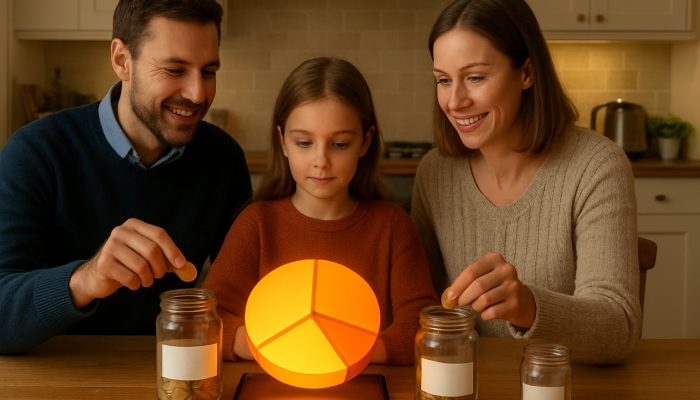
Employing structured budgeting techniques is crucial for families in the UK aiming to establish solid financial reserves. Various methods, such as the 50/30/20 rule, assist individuals in allocating their monthly income towards savings, necessary expenses, and discretionary spending. This strategy encourages consistent savings contributions, improving readiness for unforeseen financial challenges.
Regularly reviewing and modifying budgets is essential to ensure alignment with changing financial goals. By using budgeting tools and apps, individuals can gain insights into their spending patterns and identify areas for enhancement, ultimately leading to greater financial security in shifting circumstances.
Why Is It Important to Evaluate Insurance Options for Financial Protection?
Assessing different insurance options is a vital step in protecting accumulated reserves from potential losses. Residents in the UK should consider a variety of policies, including health insurance, home insurance, and income protection insurance, to ensure comprehensive coverage. These measures can alleviate the financial impact of accidents, illnesses, or property damage.
Investing in robust insurance policies not only safeguards personal assets but also brings peace of mind. By understanding the various insurance products available, residents can make informed decisions that align with their financial goals, ensuring sustained stability over time.
Professional Insights on Creating Financial Buffers for Future Resilience
Spotlighting Successful Community Initiatives Across the UK
Community initiatives throughout the UK have effectively reduced the repercussions of recent economic events through collaborative savings groups. For instance, credit unions in Wales and Scotland have provided essential financial services, enabling members to save collectively and access low-interest loans during challenging times.
These community-driven efforts have strengthened resilience among participants, highlighting the power of collaboration. By pooling resources and sharing knowledge, individuals can establish more substantial financial buffers, better preparing them to confront future economic shocks.
How Can Policy Changes Enhance Economic Resilience?
Recent adjustments to fiscal policies in the UK have created opportunities for improved support structures. For instance, revisions to tax relief for savings and investments can motivate individuals to enhance their financial reserves more effectively. Being aware of these policy changes enables residents to adjust their strategies and take advantage of new regulations.
By keeping informed about governmental changes, individuals can navigate the financial landscape with greater skill. This adaptability is crucial for improving personal stability and resilience, especially in an ever-evolving economic environment.
What Practical Steps Can Facilitate Effective Implementation?
To successfully establish financial buffers, UK residents should adopt practical strategies tailored to their specific circumstances. Start by creating a comprehensive budget, identifying areas where savings can be maximised, and defining clear savings goals. This structured approach allows individuals to consistently allocate funds to their financial reserves.
Automating savings transfers can streamline the process. By setting up direct debits to a designated savings account, individuals can prioritise saving each month. This disciplined approach fosters a culture of saving, ultimately leading to improved financial security.
Why Is Diversification Essential for Achieving Financial Security?
Diversifying investment portfolios is crucial for creating robust buffers against unexpected economic disruptions. Leading financial analysts in the UK emphasise the importance of incorporating a mix of asset classes, such as stocks, bonds, and real estate, to minimise risk and enhance overall returns. This strategy not only shields against market volatility but also opens avenues for growth.
By spreading investments across various sectors, individuals can protect their financial reserves. This diversification enables residents to better withstand economic turbulence, ensuring long-term financial stability and security in an unpredictable world.
How Can Technological Innovations Aid in Building Financial Buffers?
Modern financial technology applications are revolutionising the way individuals manage their finances in the UK. These advanced tools enable users to automate regular savings transfers, monitor spending habits, and even set financial goals. By harnessing technology, individuals can bolster their resilience against potential future economic shocks through disciplined financial management.
Utilising applications that track expenses and provide insights into spending behaviours empowers users to make informed choices. This proactive approach nurtures a culture of saving and fiscal responsibility, ultimately strengthening financial buffers.
Optimising Resource Allocation Management
Identifying Weaknesses in Supply Chain Dependencies
Examining dependencies on imports and domestic production in the UK reveals areas that require diversification to avert disruptions during supply shortages. Recent events, such as the COVID-19 pandemic, have underscored the necessity of recognising these vulnerabilities, prompting both businesses and households to reassess their resource allocation strategies.
By identifying critical supply chain weaknesses, individuals and organisations can develop contingency plans. This proactive mindset ensures preparedness for potential disruptions, protecting financial stability and access to essential goods and services.
What Strategies Support Sustainable Stockpiling?
Formulating plans for the storage of essential goods is crucial for British households aiming to ensure access during uncertain times. Focusing on non-perishable items such as canned goods, dried foods, and toiletries helps families be well-prepared for unexpected challenges, from natural disasters to economic downturns.
To stockpiling non-perishables, households should consider implementing a rotation system to manage their supplies effectively. This method minimises waste and ensures that items remain fresh and usable. Through strategic planning, families can improve their resilience and readiness for future shocks.
How Can Technology Enhance Effective Resource Monitoring?
Utilising digital tools available in the UK allows for real-time tracking of resource levels, supporting proactive adjustments to buffer systems. Numerous applications and platforms enable households to monitor their inventories, ensuring awareness of available resources and optimal times to replenish supplies.
By integrating technology into resource management, individuals can make informed decisions regarding their needs. This forward-thinking approach fosters a culture of preparedness, ensuring families are well-equipped to navigate uncertainties and maintain stability during challenging times.
Research-Backed Advantages of Establishing Financial Buffers for Future Resilience
Analysing Economic Data from Recent Challenges
Reviewing reports on UK recessions demonstrates how pre-existing buffers significantly alleviated financial pressure for many families and businesses. Data indicates that households with established emergency funds managed to navigate economic downturns more effectively, enabling them to weather financial storms without resorting to high-interest debt.
These insights highlight the importance of proactive financial planning. By creating buffers, individuals can enhance their resilience and better prepare for future economic challenges, ultimately achieving greater financial stability.
Highlighting Successful Practices from Various UK Industries
Sectors such as manufacturing have effectively employed buffer strategies to overcome past challenges in the UK. For instance, companies that implemented inventory management systems during economic downturns were able to maintain operations and protect jobs, demonstrating the effectiveness of strategic resource allocation.
These real-world examples underscore the necessity of adopting buffer strategies across diverse industries. By learning from successful practices, businesses can develop tailored approaches that fortify their resilience and ensure long-term stability in a constantly shifting market.
Exploring the Link Between Financial Security and Health
Investigating the relationship between financial security and mental health in the UK reveals the broader benefits of proactive buffer building. Research indicates that individuals with established financial reserves experience lower levels of stress and anxiety, contributing to overall wellbeing.
By prioritising financial stability, individuals can improve their quality of life. This holistic perspective acknowledges that building buffers not only protects against economic shocks but also promotes a healthier, more balanced lifestyle.
What Are the Long-Term Rewards of Building Financial Buffers?
Monitoring Progress Over Time
Assessing the effectiveness of financial buffers through annual reviews enables UK residents to refine their strategies based on evolving personal and national circumstances. Regular evaluations help individuals identify areas for enhancement and adjust their methods accordingly, ensuring ongoing relevance and effectiveness.
By setting long-term financial goals and tracking progress, individuals can remain accountable and motivated. This continuous evaluation process encourages a culture of financial responsibility, ultimately leading to sustained stability and resilience in the face of future challenges.
How Can Strategies Be Adjusted to Reflect Changing Economic Conditions?
Adapting strategies in response to interest rate fluctuations is necessary for maintaining the strength of financial safeguards in the UK. As economic conditions evolve, individuals must be ready to modify their budgets and investment approaches to ensure alignment with their financial goals.
By staying abreast of economic trends and developments, residents can make informed decisions that bolster their financial resilience. This flexibility is crucial for navigating the complexities of a dynamic financial landscape.
What Advantages Do Community Support Networks Offer?
– Strengthened relationships among neighbours
– Enhanced resource sharing during crises
– Increased access to local knowledge and skills
– Greater emotional support in challenging times
Collaborative efforts among neighbours in the UK can significantly enhance community resilience. By sharing resources and expertise, individuals can foster a supportive environment that helps everyone navigate prolonged difficulties more effectively.
How Does Financial Independence Contribute to Lasting Security?
Reflecting on sustained financial stability achieved through consistent buffering practices empowers UK residents to attain greater independence and security amid future uncertainties. By prioritising financial planning and establishing buffers, individuals can navigate economic challenges and personal transitions with confidence.
This proactive approach not only strengthens individual resilience but also cultivates a more stable and secure community. As people embrace financial independence, they promote a culture of responsibility and preparedness that benefits all.
Frequently Asked Questions
What purpose do financial buffers serve?
Building financial buffers prepares individuals for unexpected expenses or economic downturns, providing a safety net that enhances financial stability and security.
How much should I save for an emergency fund?
It is generally recommended to save three to six months’ worth of living expenses in an emergency fund to effectively cover unforeseen costs.
What government support schemes are available in the UK?
The UK offers various support schemes, including Universal Credit, Jobseeker’s Allowance, and housing benefits, to assist residents during financial difficulties.
What budgeting techniques can enhance savings?
Techniques such as the 50/30/20 rule and zero-based budgeting can help individuals allocate their income effectively, prioritising savings and essential expenses.
How can I diversify my investment portfolio?
To diversify your portfolio, consider incorporating a mix of asset classes such as stocks, bonds, and real estate, which can help mitigate risk and enhance returns.
What role does technology play in managing finances?
Technology simplifies financial management through applications that automate savings, track spending, and provide insights, assisting users in effectively building financial buffers.
How can I identify supply chain vulnerabilities?
Identifying supply chain vulnerabilities involves analysing dependencies on imports and domestic production, enabling individuals and businesses to develop diversification strategies.
What are the benefits of stockpiling essential goods?
Stockpiling essential goods ensures access during uncertainties, minimises panic buying, and allows households to maintain stability amid disruptions.
How can I monitor my resource levels effectively?
Utilising digital tools and applications can assist in tracking resource levels in real-time, enabling proactive adjustments to ensure sufficient supplies.
What are the long-term outcomes of building financial buffers?
Long-term outcomes include enhanced financial independence, improved resilience against economic shocks, and a greater sense of security and wellbeing.
Visit our Facebook profile today!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk
The Article Buffers for Absorbing Future Shocks: Essential Tips found first on https://electroquench.com